
From your first home
to your fifth.
We explain it properly, then we do the work. First home buyers, the Help to Buy scheme, refinancing and investment portfolios — across 25+ lenders, with no broker fee.
25+
Lenders on panel
$0
Broker fee
15 min
To a clear answer
“The most patient mortgage broker. A dream come true.”
— Kirra C., first home buyer
What we do
Residential lending, done properly.
We're residential specialists — homes and investment property. That focus is why we know the schemes, the policies and the lender quirks inside out.
First Home Buyers
Every grant, scheme and concession you qualify for — mapped to your situation, then matched to a lender that actually participates.
Learn moreHelp to Buy Scheme
The Federal Government co-buys up to 40% of your home. A 2% deposit, no LMI, and a much smaller loan. We'll tell you straight if you're eligible.
Learn moreBuying Your Next Home
Upgrading, downsizing or relocating. Bridging finance, porting your loan, and the timing of buying before you sell.
Learn moreRefinancing
A rate review that pays for itself, debt consolidation, or releasing equity to fund your next purchase or renovation.
Learn moreInvestment & Portfolio
Your first investment property through to a multi-property portfolio — structured so the fourth purchase is still possible.
Learn moreSelf-Employed
ABN holders, contractors and business owners. Low-doc options and lenders who read your financials properly.
Learn more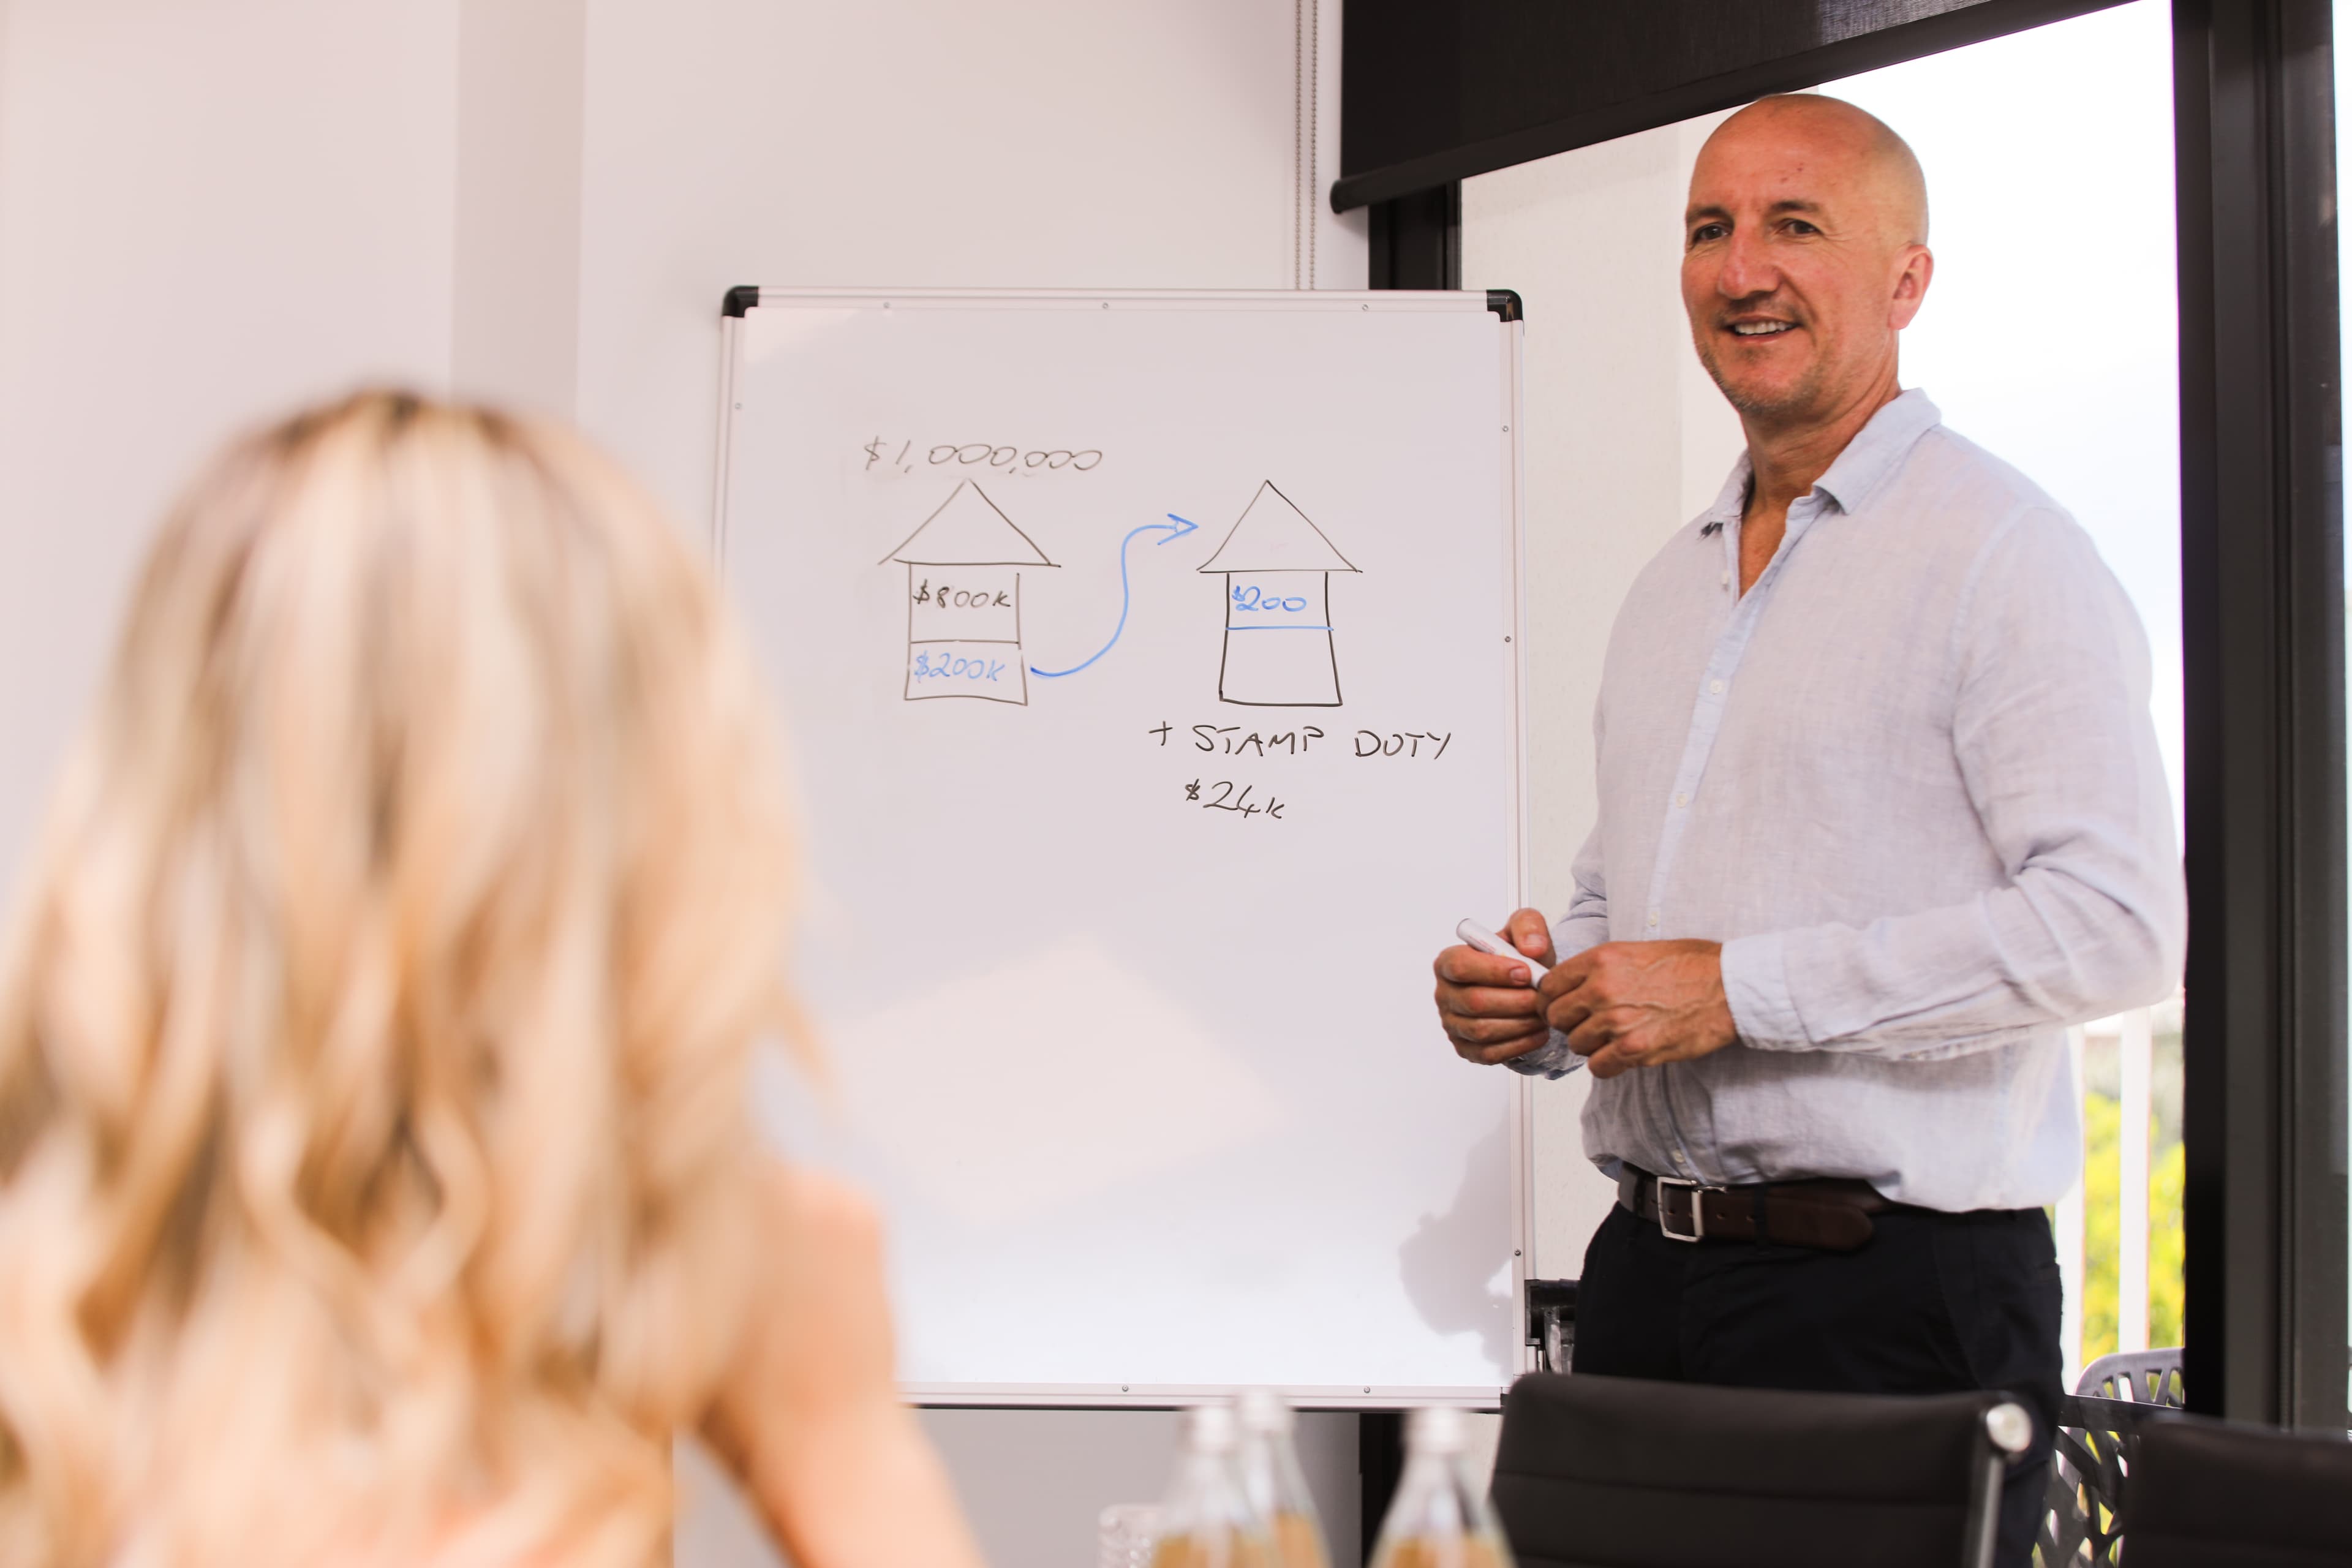
First home buyers
There is more help available than you think.
Most first home buyers know about one scheme. There are several, some of them stack, and the difference between knowing and not knowing is often tens of thousands of dollars.
- Help to Buy — the government takes an equity share of up to 40% of a new home, or 30% of an existing one. 2% deposit, no LMI.
- Home Guarantee Scheme — buy with a 5% deposit and the government guarantees the rest, so you pay no Lenders Mortgage Insurance.
- First Home Owner Grant — a cash grant for eligible buyers of a new build in Queensland.
- Stamp duty concessions — QLD first home buyer concessions can wipe out the duty entirely under the threshold.
- Guarantor loans — family equity instead of a deposit, without anyone handing over cash.
Loan types explained
Nobody should sign something they don't understand.
Guarantor, offset, split, interest-only, construction, bridging, low-doc — here's what each one actually means and who it suits.
Guarantor Loan
A family member's equity stands in for your deposit. No cash changes hands.
Fixed vs Variable
Certainty against flexibility — and why a split often beats choosing one.
Offset & Redraw
Park your savings against the loan and cut the interest you're charged.
LMI & Low Deposit
What Lenders Mortgage Insurance costs, and the legitimate ways around it.
Interest-Only
Lower repayments now, used deliberately — common on investment debt.
Construction Loan
Drawn down in stages as your build progresses. Interest only on what's drawn.
Bridging Finance
Buy the next one before the current one sells, without the fire sale.
Low-Doc & Specialist
For self-employed income that standard lender policy reads badly.
Investors & portfolio builders
Property two is easy. Property five is structure.
Most people can get a second property. The ones who get to five did something deliberate early — they kept their loans unencumbered by cross-collateralisation, spread lenders before they had to, and protected their borrowing capacity instead of spending it.
- Lender sequencing — using the strict lenders first, while you still qualify for them
- Avoiding cross-collateralisation that chains your properties together
- Equity releases timed to fund the next deposit without stalling the portfolio
- Interest-only and offset structures that keep cash flow workable as you scale
- Trust, company and SMSF lending where the structure calls for it
1st
Your first investment
Deposit, equity release and what the numbers really look like after tax.
2nd
Going again
Borrowing capacity is the constraint. We plan around it before it bites.
3rd+
Scaling up
Lender diversity, standalone security, and keeping options open.
∞
Holding it together
Annual reviews, refinances and releases that keep the portfolio moving.
How it works
Four steps, and we do most of them.
01
A free 15-minute call
Tell us where you're at. We'll tell you what's realistic, what you'd qualify for, and whether now is the right time.
02
Your strategy on paper
Borrowing power, deposit, every scheme and grant that applies, and the lenders that fit. In plain English, written down.
03
We do the application
We handle the paperwork, the lender negotiation and the back-and-forth. You sign things; we chase everything else.
04
Settlement, then a check-in
We stay on the file through settlement — and review your rate annually so the loan keeps working for you.
Russell Hall
Lead Broker & Credit Rep
Ethan Hall
Lead Broker & Property Strategist
Why Assist Loans
A father and son brokerage, small by design.
Assist Loans is run by Russell and Ethan Hall — two lead brokers who started the firm together. No call centre, no handing you to a processing team after the first meeting, and no jargon dressed up as plain English.
Russell is the credit representative on the licence and got into property by borrowing from his own mother to get started — which is roughly why he has patience for the questions people are embarrassed to ask. Ethan came from the strategy side, working for buyers agents as a property strategist, and focuses on structuring lending so a first purchase doesn't block the third.
Two sets of eyes on every file. And when we're not working, we're usually out fishing.
Common questions
Questions people actually ask.
What does a mortgage broker cost?
Nothing, in almost every case. We're paid a commission by the lender once your loan settles, and that commission doesn't change your rate — the bank pays the same whether you come through us or walk into a branch. If a situation ever required a fee, you'd know in writing before any work started.
How much can I borrow?
It depends on income, existing debts, dependants, living expenses and the lender — and different lenders can land more than $100,000 apart on the same application. The fastest honest answer is to run BorrowIQ, our borrowing power calculator, then talk it through on a call.
I don't have a 20% deposit. Can I still buy?
Yes — and most of our first home buyers don't. The main routes are the Home Guarantee Scheme (5% deposit, no LMI), Help to Buy (2% deposit with the government taking an equity share), a guarantor loan using a family member's equity, or simply paying LMI and buying sooner.
Which one suits you depends on your income, the property and your family situation. We explain each one here.
Can my parents help without giving me money?
That's exactly what a guarantor loan does. A family member offers equity in their own property as additional security — they don't hand over cash, and the guarantee is usually limited to a set amount that can be released once you've built enough equity. Full explanation here.
Do you only work with first home buyers?
No. First home buyers are a big part of what we do, but a lot of our work is refinancing and helping investors build a portfolio — second, third and fourth properties, structured so each purchase doesn't block the next one.
Where are you based?
Brisbane, working across South East Queensland including the Gold Coast and Sunshine Coast. Most of the process happens by phone, video and email, so we work with clients across Australia too.
Still wondering something? Ask us directly — it's free and takes 15 minutes.
Let's work out your next move.
A free 15-minute call. No pressure, no broker fee — just a clear answer on where you stand and what's possible.