
First home buyers
Your first home, without the guesswork.
There is more government support available than most buyers realise, and it changes regularly. We work out exactly what you qualify for, then find a lender that actually offers it.
What's on the table
Six ways first home buyers get in sooner.
Most people know about one of these. Knowing about all six is frequently the difference between buying this year and buying in three.
Help to Buy
The Federal Government takes an equity share of up to 40% of a new home or 30% of an existing one. You need a 2% deposit and pay no LMI, and because you're only borrowing against your share, the loan is far smaller.
Home Guarantee Scheme
Buy with a 5% deposit while the government guarantees the portion above 80%, so you pay no Lenders Mortgage Insurance. Places are limited and regional price caps apply.
First Home Owner Grant
A cash grant for eligible Queensland buyers building or buying a brand-new home. It's paid at settlement and can go straight toward your costs.
Stamp duty concessions
Queensland's first home concession can reduce transfer duty to nothing under the threshold and taper it above — frequently the single biggest saving available.
Guarantor loans
A parent pledges equity in their property as extra security instead of giving you cash. You can borrow up to 100% and avoid LMI, and the guarantee is released once you've built equity.
LMI waivers
Some lenders waive Lenders Mortgage Insurance entirely for certain professions — medical, legal, accounting and others — letting you borrow up to 90–95% with no premium.
Scheme rules, thresholds and price caps change. Everything here is general information — your eligibility is confirmed by the relevant authority and your lender, not by this page.
How we help
We explain it until it makes sense.
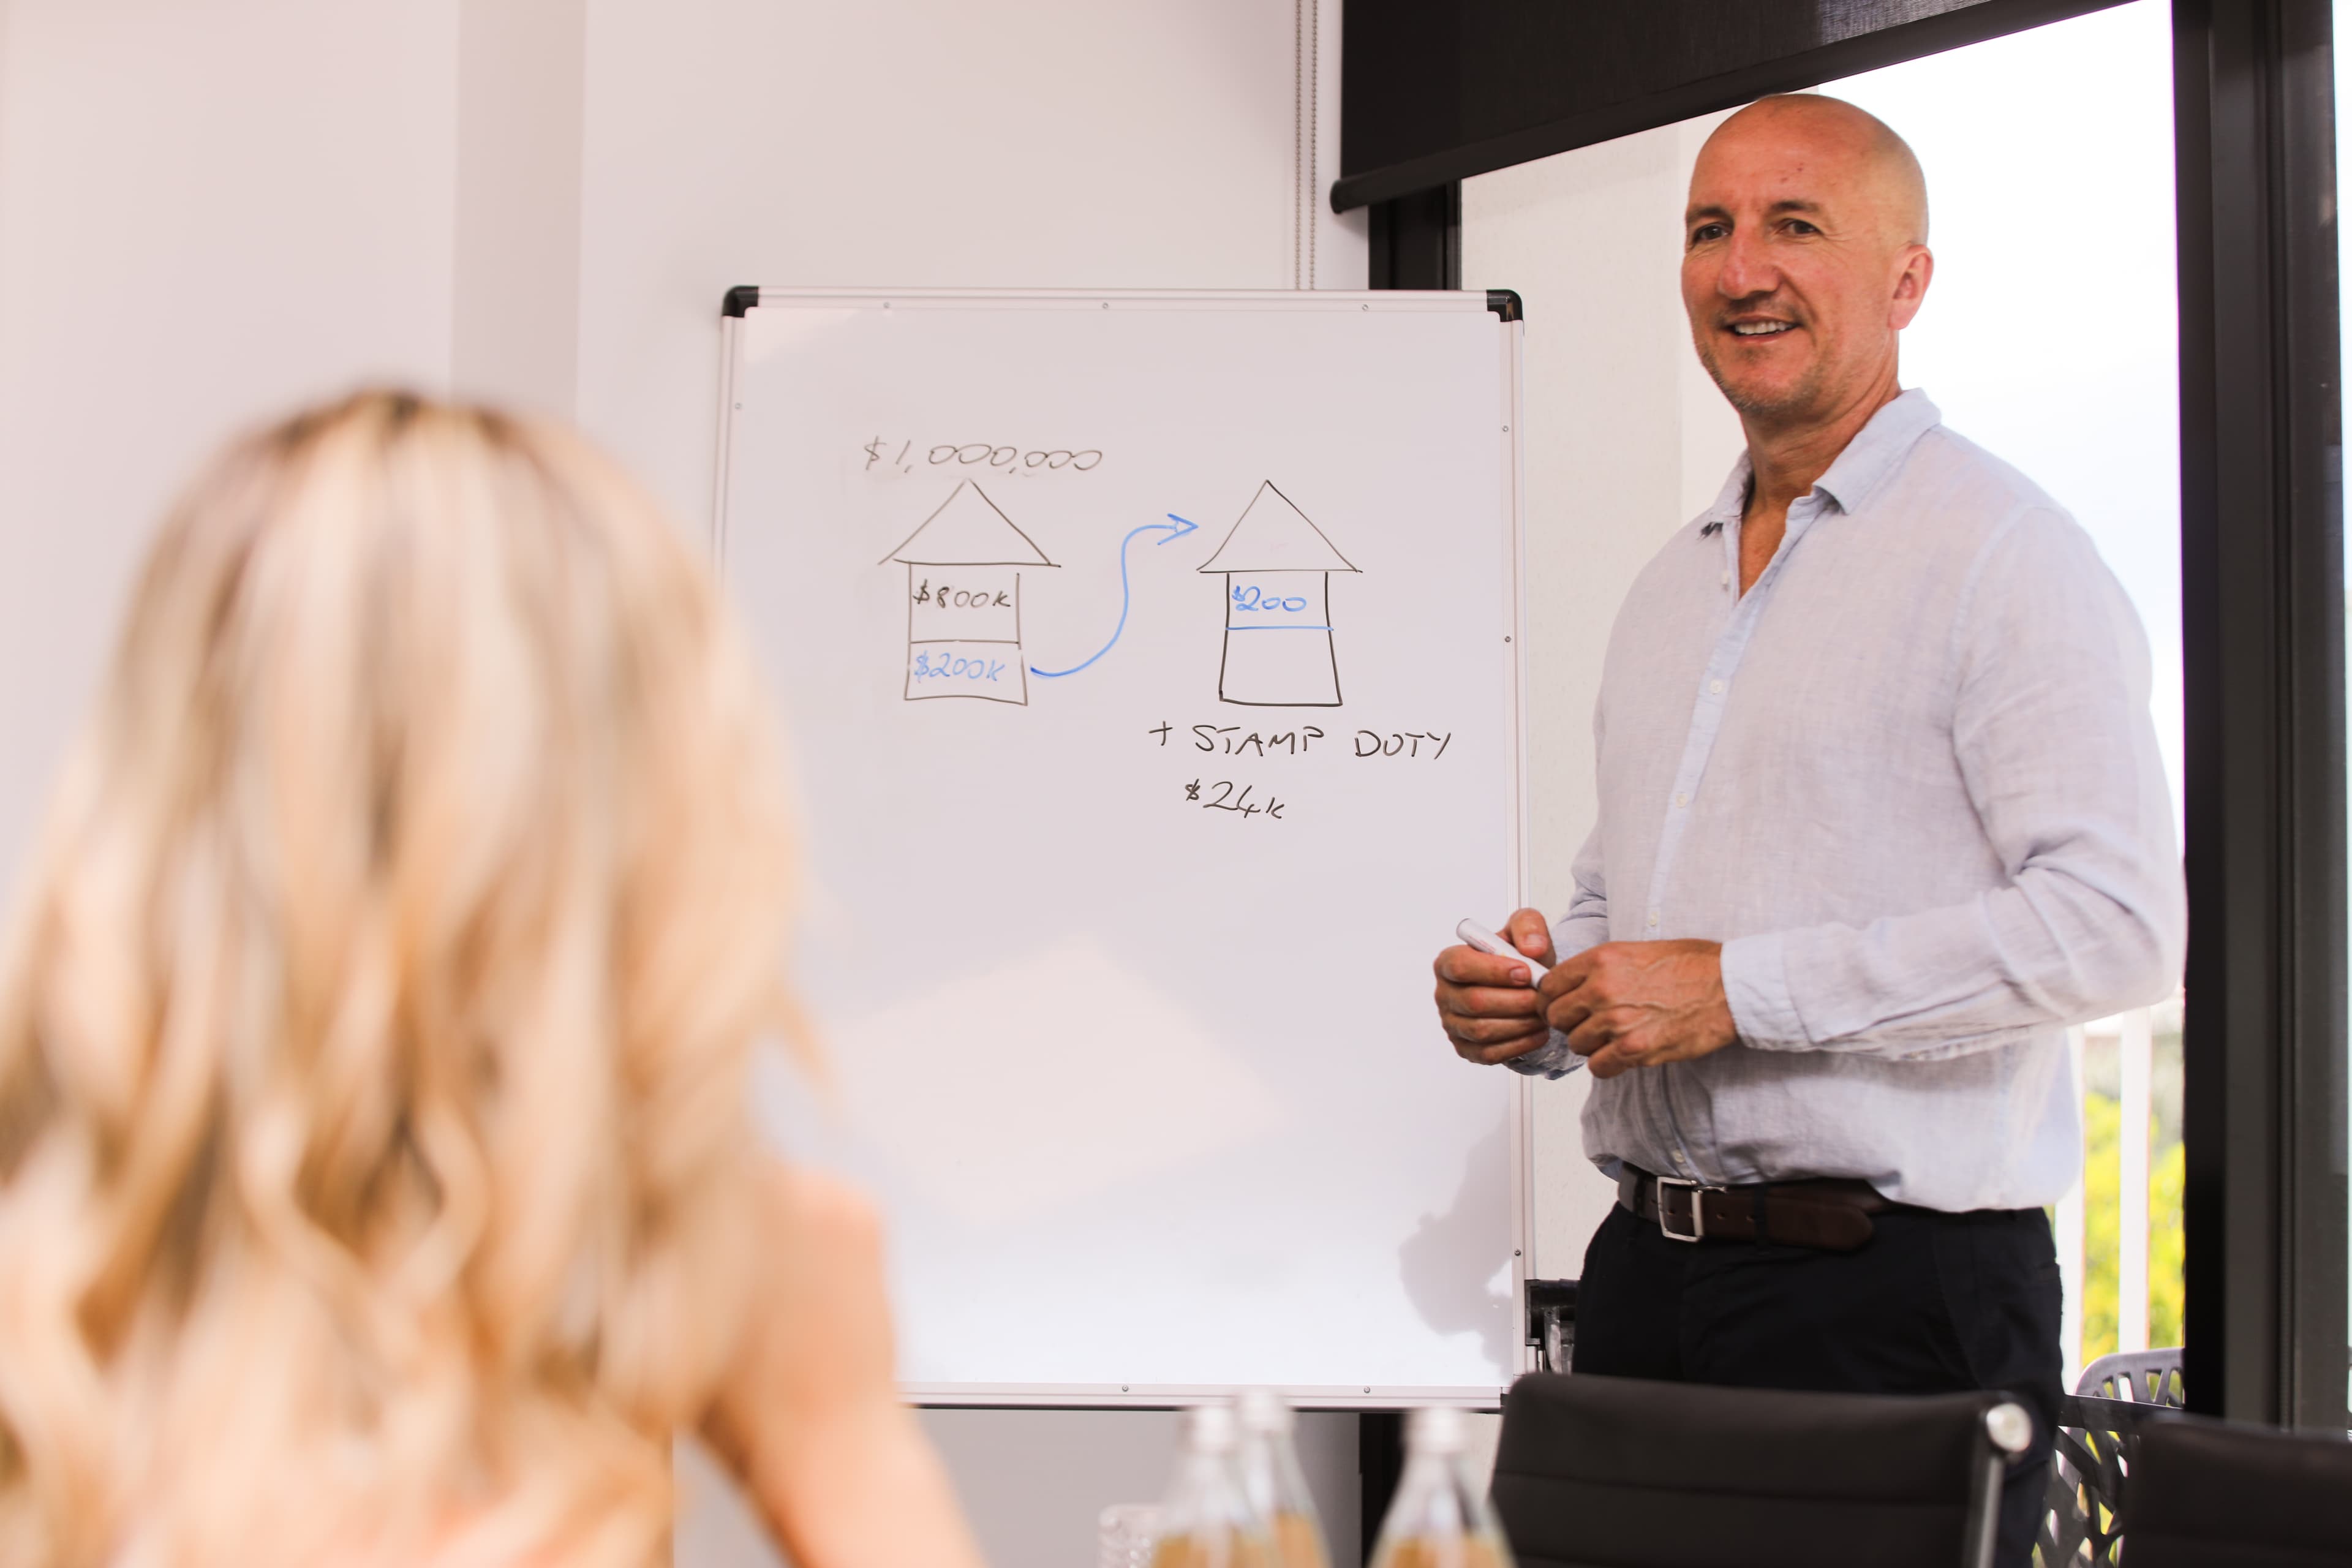
First home buyers get handed jargon and left to work it out. We do the opposite — the whiteboard comes out and we go through it until you could explain it to someone else.
- Work out your genuine borrowing power, not an income × 5 estimate
- Check every scheme, grant and concession against your actual situation
- Find lenders that participate in the scheme you qualify for — not all do
- Get you pre-approved so you can bid or offer with confidence
- Handle the application, the paperwork and the lender from there to settlement
- Review your rate once a year afterwards, because the first rate rarely stays the best one
The deposit problem
You probably need less than you think.
Four routes in, depending on your situation.
2%
Help to Buy
Government equity share, no LMI.
5%
Home Guarantee Scheme
Government guarantee, no LMI.
0%
Guarantor loan
Family equity as security instead.
5–15%
Pay LMI and go
Sometimes cheaper than waiting.
First home buyer FAQ
The questions we get every week.
How much deposit do I actually need?
Less than you've probably been told. Help to Buy starts at 2%, the Home Guarantee Scheme at 5%, and a guarantor loan can get you in with no deposit at all. Even without any scheme, 5–10% plus LMI is a normal path. The 20% figure is a default, not a requirement.
Can I use more than one scheme at once?
Sometimes. Stamp duty concessions generally sit alongside other support, and the First Home Owner Grant can apply to a new build you're also financing under a scheme. Help to Buy and the Home Guarantee Scheme, though, are alternatives rather than a stack. Which combination works depends on your income, the property type and the price — that's exactly what we map out on the first call.
Does a HECS/HELP debt stop me buying?
No, but it reduces your borrowing capacity because the compulsory repayment comes out of your assessable income. Lenders treat it differently from each other, and if your balance is small enough to clear outright, paying it off before applying can sometimes lift your capacity by more than the balance itself. Worth checking before you apply, not after.
What will it cost me beyond the deposit?
Budget for transfer duty (often reduced or nil for first home buyers), legal or conveyancing fees of roughly $1,500–2,500, building and pest inspections around $600–900, lender fees, and moving costs. We give you a full written estimate before you make an offer, so nothing lands as a surprise at settlement.
How long does the whole process take?
Pre-approval usually takes a few days to two weeks depending on the lender and how complete your documents are. From an accepted offer to settlement is typically 30–45 days in Queensland. The part you control is having your paperwork ready — that's where most delays come from.
Let's find out what you qualify for.
Fifteen minutes, no cost, no obligation — and most people leave the call knowing more about their options than they've picked up in months of searching.